The subtraction nobody questions
Every consolidated report ends in the same operation. Add up what the family owns, subtract what it owes, and call the result net worth.
The addition gets all the engineering. Custodian feeds, reconciliation, look-through into funds, valuation policies for private companies and real estate. The subtraction gets one line, usually typed in by hand, often months old.
That asymmetry rests on a premise so obvious nobody writes it down: a liability is a number. You owe a bank four million dollars, so you subtract four million dollars. Done.
The premise is wrong in a specific and expensive way. A lombard loan is not a number. It is a contract with a floating rate, a maturity, a list of pledged assets, a lending value for each of them that the bank can revise, and a trigger that turns a market move into a forced sale. A capital commitment is not a number either, and neither is a personal guarantee, a tax bill waiting on a gain, or a loan from a father to his son's holding company.
Each of these behaves. And the defining feature of their behavior is that it gets worse at the same moment the assets do.
A system that records debt as a balance can tell a family what it owes. It cannot tell them what that debt will do to them next quarter. In most private portfolios, the second question is the one that decides outcomes.
A family that looks conservative
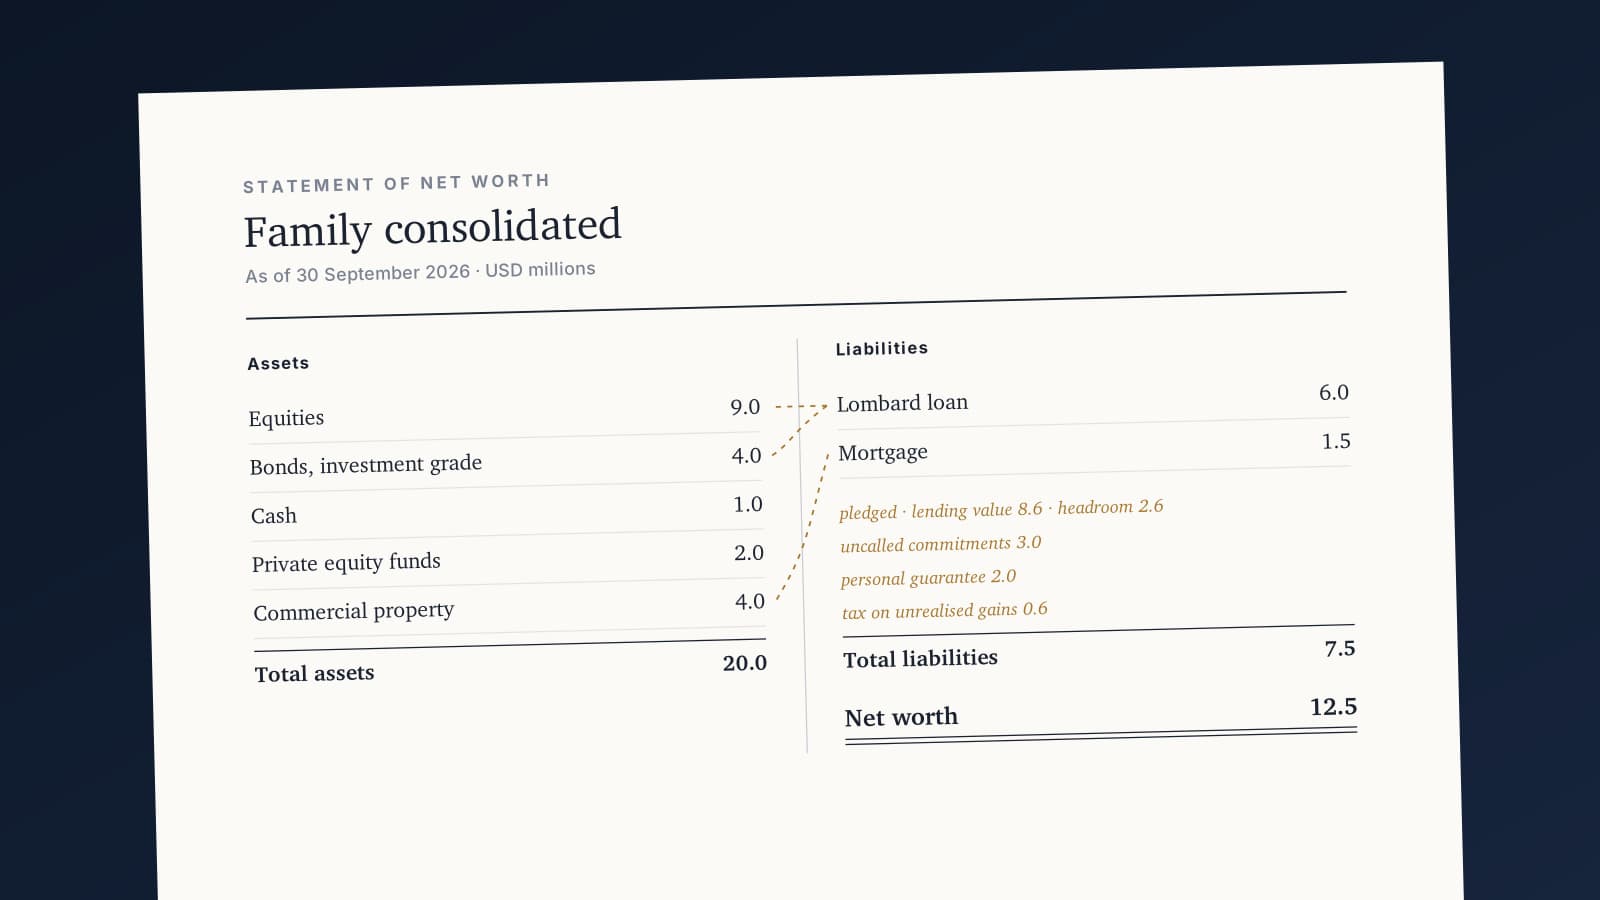
A family with $20 million in gross assets. Nothing exotic. A discretionary portfolio at a private bank, some cash at a second bank, a few private equity funds and a commercial building held through a family holding company.
| Asset | Where it sits | Value |
|---|---|---|
| Equity portfolio | Private bank A | 9.0 |
| Bond portfolio, investment grade | Private bank A | 4.0 |
| Cash | Bank B | 1.0 |
| Private equity funds (NAV) | Fund administrators | 2.0 |
| Commercial property | Family holding company | 4.0 |
| Gross assets | 20.0 |
Three years ago the family drew a lombard loan against the bank portfolio, to fund the private equity programme without selling equities with large embedded gains. The holding company carries a mortgage on the building. And the father has personally guaranteed the credit line of the family's operating business, which is not part of the managed wealth at all.
| Obligation | Terms | Amount | On the balance sheet? |
|---|---|---|---|
| Lombard loan | Floating, about 5% all-in, rolled yearly, secured on the bank A portfolio | 6.0 | Yes |
| Mortgage | 5.5% fixed, holding company, matures 2028 | 1.5 | Yes |
| Uncalled PE commitments | Callable on 10 days' notice | 3.0 | No |
| Personal guarantee | Operating company credit line | 2.0 | No |
The bank lends against the pledged portfolio at 60% of the value of equities and 80% of investment-grade bonds. That gives a lending value of $8.6 million against a loan of $6 million: 70% utilisation, $2.6 million of headroom. (The lending values are assumptions for this illustration; actual advance rates depend on the facility, the assets pledged and the lender's policy.)
Now the report. Most platforms record the loans the only way their data model allows: as positions with a negative value, usually inside fixed income. The lombard lands there naturally, because it sits in the bank portfolio next to the bonds. The mortgage follows when the holding company is consolidated: its debt has to go into some asset class, and fixed income is the only one built for a rate and a maturity. (Some firms net the mortgage against the building instead, which hides it in a different way: real estate shows $2.5 million and the debt disappears.) With both loans in fixed income, the quarterly allocation comes out like this:
| Asset class | Value | Weight |
|---|---|---|
| Equities | 9.0 | 72% |
| Fixed income | −3.5 | −28% |
| Cash | 1.0 | 8% |
| Private equity | 2.0 | 16% |
| Real estate | 4.0 | 32% |
| Net worth | 12.5 | 100% |
Every number is arithmetically correct. And the report answers none of the questions that matter.
It says the family has negative fixed income, which is not a position anyone holds. It says equities are 72% of the portfolio, without saying that this is 72% of a number that is itself leveraged 1.6 times. It does not show that a 10% fall in equities costs $900 thousand, which is 7.2% of net worth, not 4.5%. It does not show the $2.6 million of headroom, the only measure of how close the family is to a forced sale. It does not show the $3 million of capital that can be called on ten days' notice, against $1 million of free cash. And it has nowhere at all for the guarantee.
The family's adviser knows most of this. It lives in his head, in a spreadsheet and in the bank's credit statement. It does not live in the system that produces the report, the risk limits and the invoice.
Why a negative bond is not a loan
The standard workaround deserves a fair hearing, because it is not foolish. A loan does look like a short bond. It has a principal, a rate and a maturity. Book it as a fixed income position with a negative quantity, let it accrue interest, and net worth comes out right. Many firms use this approach for years without an obvious problem.
The workaround answers exactly one question: how much does the family owe today? Everything else a firm needs from a liability, it either gets wrong or cannot represent.
| What the firm needs to know | What a negative bond gives |
|---|---|
| How much is owed today | Correct |
| Allocation of the family's wealth | Distorted: debt shows up as negative fixed income, and every other weight is inflated by leverage that is never named |
| Interest rate sensitivity | Misleading for floating loans: a lombard has little sensitivity to the reference rate between resets, while its spread, renewal terms and availability can change sharply. A bond line models none of that |
| Which assets secure which loan | Not representable: a position has no link to the positions pledged against it |
| Distance to a margin call | Not representable: no lending values, no haircuts, no utilisation, no headroom |
| Return of the fixed income sleeve | Can change sign (next sections): a loss reported as a gain |
| Cost of financing in attribution | Buried inside fixed income returns, then charged to whoever picked the bonds |
| Uncalled commitments and guarantees | Not representable: no quantity can describe something that has not happened yet |
| Loans between family entities | Not representable: no counterparty, so nothing to eliminate on consolidation |
| Billing base | Silently net of debt, by accident rather than by decision |
The pattern is the same in every row. The workaround converts an obligation into the only thing the system knows how to hold, a position with a value. Whatever is not a value is lost on the way in. And most of what matters about debt is not a value: it is a relationship to other assets, a condition that triggers an event, a cash flow on a date.
None of this is fixed by a better asset class label. A dedicated "liabilities" bucket makes the allocation chart prettier and leaves every other row of the table exactly as it was.
Debt that moves with the market
Take a bad year, not a catastrophe. Equities fall 25%. Credit spreads widen and the bond portfolio loses 4%. Private equity marks come down 15%, the building is revalued 10% lower. The kind of year that arrives once or twice a decade.
The asset side of the report handles this well. Every line is revalued, the allocation shifts, performance turns red. What it cannot show is the sequence on the other side.
First, the collateral shrinks. The pledged portfolio falls, and the lending value falls with it, faster than net worth suggests.
Second, the bank changes the rules. Many facility agreements let the lender revise lending values at its discretion, and stressed markets are exactly when lenders use that right. Suppose the bank cuts the lending value on equities from 60% to 50%. Nothing in the family's portfolio moved. Their headroom did.
And the bank may not renew the line at all. A lombard is usually a short-term facility rolled each year. At renewal, in a systemic crisis or when the lender's own balance sheet is under pressure, the bank can decline to roll it, and the full $6 million falls due whatever the headroom. Headroom measures the distance to a call. It says nothing about the distance to a maturity the lender may choose not to extend.
Third, the capital calls keep coming. Private equity managers tend to keep calling capital in a downturn, while distributions slow down, because exits get postponed. The family's free cash was sized against a world in which distributions recycle into calls. That world just paused.
| Step | Lending value | Loan | Headroom | Utilisation |
|---|---|---|---|---|
| Before the shock | 8.60 | 6.0 | 2.60 | 70% |
| Markets fall (equities −25%, bonds −4%) | 7.12 | 6.0 | 1.12 | 84% |
| Bank cuts equity lending value to 50% | 6.45 | 6.0 | 0.45 | 93% |
| Family sells pledged bonds to fund the year (below) | 6.14 | 6.0 | 0.14 | 98% |
| Item | Amount |
|---|---|
| Free cash at bank B | +1.00 |
| Capital calls (a third of the uncalled commitments) | −1.00 |
| Lombard interest | −0.30 |
| Mortgage interest | −0.08 |
| PE distributions | 0.00 |
| Shortfall | −0.38 |
The shortfall has to come from somewhere, and the only liquid assets are the pledged ones. Selling $380 thousand of bonds and moving the cash out of the pledged account costs 80 cents of headroom for every dollar raised. After that, a further fall of just over 4% in equities exhausts the headroom and triggers the call, if nothing else changes. At that point the bank sells, at the bottom, on its own timetable.
Three things stand out.
None of the steps is unusual. Each would pass a risk committee on its own: a moderate loan, a reasonable programme of commitments, a normal level of cash.
The risk is in the correlation. The collateral falls, the lending value is cut, the calls arrive and the distributions stop, all for the same reason and in the same quarter. A system that records each obligation as an independent balance cannot see that they are one exposure.
And the liquidity the family was counting on was never there. Before the shock, the $2.6 million of unused credit was, in practice, the family's emergency reserve. It is the first reserve to disappear in a crisis, because the lender is the one who decides when it is available.
The guarantee sits underneath all of this. In the same recession, the family's operating company is the business most likely to draw its credit line and least likely to repay it. A guarantee is called when the guarantor is weakest. That is not bad luck. It is the design of the instrument. It stays out of the cash table above because it is contingent. But if the operating company defaults and the bank calls the guarantee in full, the year's shortfall goes from $380 thousand to $2.38 million, with no headroom left to absorb it. The forced sale is immediate.
The return that changes sign
Leverage does not only change risk. It changes what a return means, and the negative-bond workaround makes that visible in an uncomfortable way.
Go back to the family before the shock and give it a good year instead. Equities, private equity and the building return 8%. The bonds return their 5% coupon with no price change, and cash earns 4%. In aggregate, the assets return 7.2%. The family's combined debt of $7.5 million, the lombard plus the mortgage, costs about $383 thousand a year in interest, roughly 5.1%.
Look at the fixed income sleeve as the platform sees it. It starts the year at −$3.5 million: $4 million of bonds minus $7.5 million of loans. Over the year it earns $200 thousand of coupons and pays about $383 thousand of interest. The sleeve lost about $183 thousand.
Apply the simplest return formula, change in value divided by starting value, and the result is −0.183 divided by −3.5. That is +5.2%.
The sleeve lost money and the report says it gained. This is not a rounding issue or an edge case. It is what any return formula does when the denominator is negative. And when a firm's bonds and loans are close in size, the denominator approaches zero and the reported return runs to hundreds of percent, in either direction, on a sleeve whose economics barely moved. Systems that use the absolute value of the denominator get the sign right in this case, but they have no meaningful base at all when the sleeve crosses from net assets to net debt during the period.
The fix is not a better formula for the sleeve. It is to stop putting the loan in the sleeve. The method has existed for decades in performance measurement, and it is the same one our article on synthetic positions applied to derivatives: separate the asset leg from the financing leg, and let each carry its own weight and return.
| Line | Weight | Return | Contribution |
|---|---|---|---|
| Assets | 160% | 7.2% | +11.5% |
| Financing | −60% | 5.1% (cost) | −3.1% |
| Net worth | 100% | +8.5% |
Read this way, the story is clear. The assets delivered 7.2% on what was managed. Under these assumptions, borrowing added 1.3 points net of its cost; in a year when the assets earn less than the debt costs, it subtracts instead. Both results are true, and they belong to different people: the first to whoever ran the portfolio, the second to whoever decided on the loan.
The same table explains the bad year. Gross assets lost 15.6%. With debt balances held constant, net worth lost 28%: the asset loss multiplied by 1.6, plus a year of interest. A report that shows only the first number is showing the managers' year. A report that shows only the second is showing the family's year without saying why it was worse. A family that borrows needs both, side by side, with the financing leg between them.
Without that separation, the cost of debt always lands somewhere it does not belong. Inside fixed income, it makes the bond manager look bad. Inside net worth, it disappears into a lower number nobody can decompose. It is the same pattern as carry in a synthetic position: what the measurement system cannot name, it charges to the manager.
Obligations nobody has signed for yet
The loan and the mortgage are the easy part. They exist, someone sends a statement, and the balance is a fact. Most of what a family owes is not like that. It is an obligation that has not happened yet, or one that exists only as a consequence of something else.
It helps to separate three states, because they behave differently and must never be added up as if they were the same thing.
| State | Examples | What defines it |
|---|---|---|
| Drawn | Lombard loan, mortgage, holding company debt, margin loan | A balance that accrues interest and has a schedule |
| Committed | Uncalled capital commitments, personal guarantees, letters of credit | A promise whose amount is known but whose timing is not, or whose trigger is someone else's failure |
| Latent | Tax on unrealised gains, performance fees not yet crystallised | An economic exposure created by the asset itself, which becomes an obligation when something is sold or crystallised |
Committed obligations are where the timing risk lives. An uncalled commitment is cash the family has promised but still holds, which means it appears on the asset side of the report as free liquidity. In our example, the $1 million of cash at bank B looks like a 5% liquidity buffer. Against $3 million of callable commitments, it is not a buffer at all. It is a down payment.
The mirror image matters just as much. An undrawn credit line is a contingent asset: liquidity the family can tap. As the previous section showed, it is the kind that evaporates under stress. Both belong in a liquidity view. Neither belongs in net worth.
Latent obligations are the most underestimated, because they hide inside asset values. Suppose the family's equity portfolio carries $3 million of unrealised gains. At an assumed 20% rate, those gains carry a potential $600 thousand tax cost the day they are realised, and a margin call is exactly what forces a sale. The amount and timing depend on the jurisdiction; the exposure is common. The same logic helps explain why the family borrowed in the first place: the immediate tax cost of realising the gains may have exceeded the expected cost of borrowing over the period considered. In some jurisdictions, borrowing against appreciated assets can defer realisation, and the associated tax, for an extended period. Whether that remains attractive depends on financing costs, collateral risk, tax rules and the family's liquidity needs, and the system can weigh none of them, because it sees neither side of the trade-off. It also makes a margin call more expensive than it first appears: a forced sale may require the family to repay the lender and crystallise a tax liability at the same time, with the amount and timing set by the applicable rules. The debt is on the report. The tax is not.
Loans inside the family break consolidation in a quieter way. The father lends $2 million to his son's holding company to buy an apartment. In the father's portfolio, the loan is a $2 million receivable. In the son's, there is a $2 million apartment and a $2 million debt. Consolidate the family and three things can happen:
- Both sides are recorded and eliminated against each other. Family net worth is correct.
- Both sides are recorded and not eliminated. Nothing is double counted in net worth, but the family's gross assets and gross debt are both inflated by $2 million, and leverage looks higher than it is.
- The father's receivable and the son's apartment are recorded, but the matching debt is missing, because it is not held at any bank and nobody typed it in. Family net worth is overstated by $2 million.
The third case is a recurring risk wherever reporting is fragmented. Elimination is impossible if the system does not know that the receivable and the debt are two ends of the same contract, and a negative bond has no other end.
The fee with two bases
The firm charges 80 basis points on the family's wealth. On which number?
| Billing base | Amount | Annual fee |
|---|---|---|
| Gross assets | $20.0 m | $160 thousand |
| Net worth | $12.5 m | $100 thousand |
Sixty thousand dollars a year depends on a definition, and in most firms nobody chose it. If the loans are booked as negative bonds inside the billable portfolio, the base becomes net worth automatically. If they are kept outside, the base becomes gross. Either way, the firm's revenue was set by a modelling shortcut someone took during onboarding.
Both answers are defensible, and each has a cost the firm should accept knowingly.
Billing on gross assets reflects the work: the firm manages $20 million of assets, whatever financed them. But it means the firm earns more when the client borrows more. That is a conflict a client can reasonably ask about, and one that compliance teams should expect to be examined whenever an adviser recommends borrowing against a portfolio.
Billing on net worth reduces the incentive to grow the fee base through leverage and ties the fee to what the family owns after debt. But the firm earns less for managing exactly the same assets, and earns least in the year leverage made the work hardest. Neither base is neutral.
There is a third party in the picture, too. The bank that granted the lombard earns a spread on it every year. When the lender and the adviser belong to the same group, that spread is revenue the firm receives without invoicing it, the same kind of line we described in Half Your Revenue Never Touches an Invoice.
The point is not which base is right. It is that the base should be a written decision per mandate, visible on the invoice, and computed by a billing engine that knows the difference between an asset and a debt. A negative bond guarantees that the decision is made by accident, and that nobody can explain it when the client asks.
Three systems, three halves
If debt matters this much, why do so few platforms model it? For the same reason as with synthetic exposure: lineage. Each category of software that touches a family's balance sheet was born solving a different problem, and each holds a different half of the picture.
Portfolio and consolidation platforms were built on custodian feeds. A custodian reports what it holds, and what it holds are assets. The entire data model grew from that starting point: positions, prices, transactions, performance. Liabilities arrived later, as a request from family offices, and were fitted into the only structure available. Hence the negative bond, or a manual "loan" asset class with a negative value. The platforms can show the balance. They were never designed to know what it is attached to.
Family office accounting systems come from the opposite direction. They are built on a general ledger, so a liability is native: double entry guarantees that every loan has a counterpart, and loans between entities can be eliminated. But a ledger records what happened, valued at book or at the last statement. It has no notion of a lending value, a haircut, a scenario or a correlation. It knows the debt exactly and has no idea how it will behave.
The lender's own credit system knows the behaviour precisely. It tracks lending values, haircuts, utilisation and call triggers in real time, because that is how the bank protects itself. But it sees only its own loan and its own collateral. It does not know about the private equity commitments, the cash at the other bank, the guarantee or the son's apartment. It is precise about a fraction of the problem, and it shares that fraction as a monthly PDF and a letter when terms change.
Put the three side by side and the gap is obvious. The risk in the example above comes from the interaction between obligations: collateral falling while calls arrive and the guarantee becomes live. Each system holds one or two of those pieces. None holds all of them. And the interaction is exactly what nobody is responsible for seeing.
This is not a failure of any vendor. It is a consequence of which problem each one was built to solve. What changed is the private balance sheet. Leverage against portfolios, private markets programmes and complex holding structures used to be the exception in wealth management. For many complex family portfolios, they are no longer the exception.
What a system would have to do
None of this needs new finance. Lenders have computed lending values for a century, fund accounting has separated financing legs for decades, and ledgers have eliminated intercompany loans for longer than either. What is missing is a data model that holds all of it in the same place as the assets. Eight requirements:
- The liability is its own object, not a negative asset. It carries principal, currency, rate type, index and spread, reset dates, maturity, amortisation schedule, accrued interest, the entity that owes and the lender. It never sits inside an asset class, and it never enters a return calculation as a position.
- Collateral is a link, not a location. Each secured liability points to the accounts or positions pledged against it, with a lending value per asset type. Haircuts are versioned over time, because the lender can change them and the history of those changes is evidence. From this the system derives lending value, utilisation, headroom and the market move that would trigger a call.
- Three states, reported separately. Drawn, committed and latent obligations each have their own view. Committed and latent amounts never enter net worth silently, and the three are never summed into a single number, for the same reason risk factors are not.
- Two net worths, both visible. Gross assets and net worth are shown side by side, each with its own return. Attribution carries an explicit financing leg, so the cost of debt is charged to the decision to borrow and not to the manager of the assets.
- Obligations are stressed together with the assets. A scenario moves the collateral, applies the lender's haircut policy, accelerates capital calls, pauses distributions and flags guarantees whose underlying business is exposed. The output is a dated liquidity path, not a revalued balance.
- Every obligation has two ends. A loan between family entities is recorded once, with both parties, so that consolidation eliminates it by construction and an unrecorded counterpart is detected rather than ignored.
- The billing base is a declared rule. Gross, net or managed assets, chosen per mandate, applied by the billing engine and printed on the invoice.
- Lender data comes in structured and reconciled. Credit statements, rate resets and haircut letters are extracted into the model and reconciled against the lender's figures, the same way custodian positions are reconciled today.
None of these is exotic. All of them are assumptions that a system built around "a liability is a number" will not satisfy by accident.
This is the model Pivolt has been built on. The reason is the same conviction behind our consolidation and scenario work: a family's wealth should be described the way it actually behaves, in one place, with every number traceable to its source. A balance sheet where the assets are modelled in depth and the debts are a single line is not half right. It is wrong in the direction that hurts.
What the subtraction hides
Go back to the family's quarterly report. Net worth of $12.5 million, a diversified allocation, a modest line of negative fixed income nobody looks at twice. It is a correct report. It is also the report of a family that is one bad year, one haircut letter and one capital call away from a forced sale, and nothing on the page says so.
The industry spent two decades learning that the asset side of a private balance sheet cannot be reduced to market values: alternatives have cash-flow timing, structures have look-through, synthetic positions have exposure. The liability side is the same lesson, still waiting to be applied.
Net worth is not a sum. It is the difference between what a family owns and a set of obligations with their own terms, triggers and timing, and the most important thing about that difference is how it changes when everything else does.
The subtraction is correct. It is just not the question that matters.